Owning a home comes with many responsibilities, from routine maintenance to preparing for unexpected repairs. A sudden fire, severe weather event, or break-in can lead to expensive losses that may be difficult to manage without financial protection. Homeowners insurance can help reduce the financial impact of certain unexpected events by covering eligible losses according to the terms of your policy.
Whether you recently purchased a property or want to review your existing protection, understanding homeowners insurance can help you choose coverage that suits your home, belongings, and budget.
Understanding How Homeowners Insurance Works
Homeowners insurance is a policy that provides financial protection against specified risks affecting your property and, in some cases, your personal liability. In exchange for paying a premium, you receive coverage for eligible losses described in your insurance agreement.
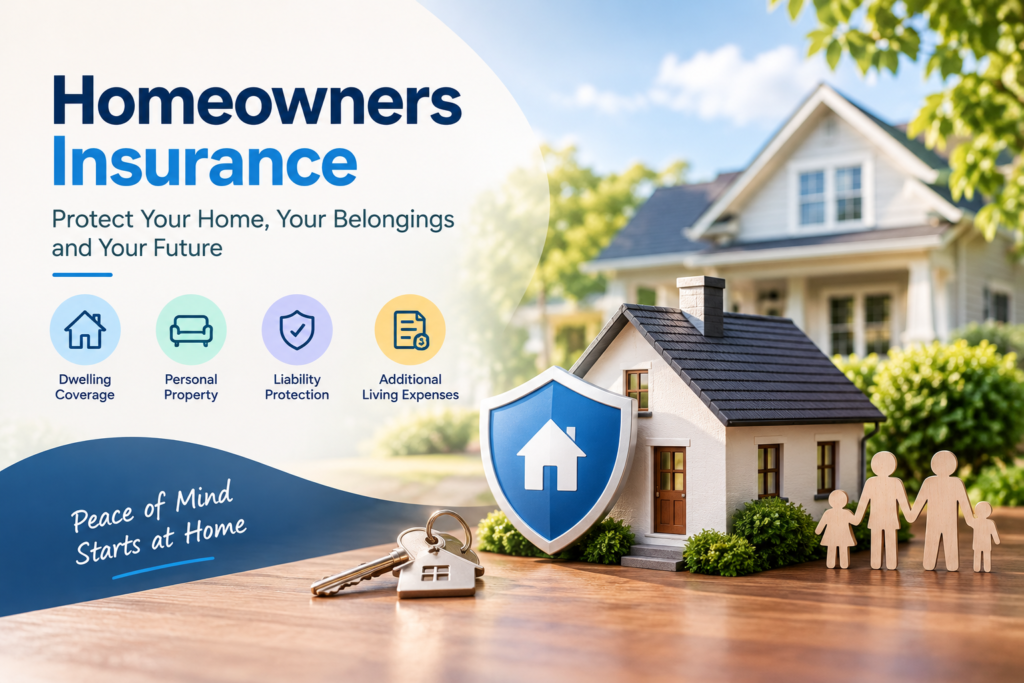
Depending on the policy, protection may extend to your home’s structure, personal possessions, liability claims, and certain extra expenses if a covered incident temporarily prevents you from living in your home.
However, coverage is never unlimited. Insurers establish specific coverage amounts, deductibles, exclusions, and conditions that determine when benefits may be available.
Important Types of Home Insurance Coverage
Home insurance policies can combine several forms of protection. Understanding what each one does can help you evaluate different quotes more effectively.
1. Protection for Your Home’s Structure
Dwelling coverage is designed to help pay for covered damage to the physical structure of your house. This may include the roof, walls, floors, and permanently installed components.
For example, if a covered fire damages part of your home, this coverage may help pay for eligible repair or rebuilding costs, subject to your policy’s terms.
When selecting a coverage limit, consider the estimated cost of rebuilding your home rather than relying solely on its market value.
2. Coverage for Personal Belongings
Furniture, clothing, computers, kitchen appliances, and other household possessions can represent a substantial investment.
Personal property coverage may help repair or replace eligible belongings following a covered event, such as certain types of theft or fire damage.
Review your policy’s limits carefully. Some expensive items may have special coverage restrictions, and you may need additional protection for valuables such as jewelry, collectibles, or specialized equipment.
3. Personal Liability Protection
Homeowners may face financial responsibility if someone is injured on their property or if they accidentally cause certain types of damage to another person’s property.
Personal liability coverage may help with eligible legal expenses, settlements, or damages, depending on the circumstances and policy conditions.
Check the liability limit when comparing policies, particularly if you want protection against potentially costly claims.
4. Temporary Living Expenses
A serious covered loss can sometimes make a property unsuitable for living in while repairs are completed.
Additional living expenses coverage may help pay certain necessary costs above your normal living expenses, such as temporary accommodation, when the policy’s requirements are met.
Coverage limits, qualifying events, and the duration of available benefits vary by policy.
5. Other Structures on Your Property
Some homeowners policies also provide coverage for qualifying structures separate from the main house. These may include detached garages, sheds, or fences.
The protection available depends on the policy and its limits. If you have multiple structures on your property, check whether the coverage provided is sufficient.
Which Events May Not Be Covered?
One of the most important steps in choosing homeowners insurance is understanding its exclusions.
Depending on your policy, coverage may not include:
- Flood damage: Flooding often requires separate flood insurance.
- Earthquake damage: Separate earthquake coverage may be necessary.
- Maintenance issues: Neglect, deterioration, and ordinary wear and tear are generally not covered.
- Certain water damage: Gradual leaks, sewer backups, or other water-related losses may be excluded or subject to special conditions.
- Intentional damage: Losses resulting from deliberate acts may not qualify for coverage.
These examples are not universal rules for every policy. Endorsements and additional coverage options may change the protection available, so review your insurance documents carefully.
What Determines the Price of Homeowners Insurance?
There is no single price that applies to every homeowner. Insurance companies evaluate several details when calculating premiums.
Factors that may influence your quote include:
- Property location: Local weather risks, wildfire exposure, crime rates, and rebuilding costs can affect pricing.
- Home characteristics: The property’s age, construction materials, roof condition, and size may influence the premium.
- Rebuilding expenses: The estimated cost of repairing or reconstructing the home is an important consideration.
- Coverage selections: Higher limits and optional protections can increase the overall cost.
- Deductible amount: Your selected deductible can affect your premium and out-of-pocket responsibility.
- Claims history: Previous claims may influence eligibility or pricing.
- Protective features: Certain alarms, security systems, or eligible safety improvements may qualify for discounts.
Because insurers assess these factors differently, requesting several quotes can help you understand your available choices.
How to Find and Compare Home Insurance Quotes
Comparing insurance quotes is about more than finding the lowest premium. Two policies with similar prices may provide different levels of protection.
Follow these steps to make a more informed comparison.
Step 1: Gather Your Property Information
Prepare basic details about your home, including its location, approximate age, construction type, roof condition, and major safety features. Accurate information can help insurers provide more relevant estimates.
Step 2: Decide What Protection You Need
Consider the estimated rebuilding cost, the value of your belongings, your liability protection needs, and any additional risks associated with your property.
Step 3: Request Multiple Quotes
Contact insurance providers individually or explore a quote-comparison service. Check which companies are included and whether the service connects you directly with insurers or another type of provider.
Step 4: Compare Equivalent Coverage
Review the dwelling limit, personal property protection, liability limit, deductible, exclusions, and optional benefits for each quote.
Using similar coverage levels makes it easier to identify meaningful differences between offers.
Step 5: Review the Final Policy
Before purchasing, read the policy documents and confirm the premium, payment schedule, coverage conditions, and exclusions. Make sure you understand what you are buying.
Practical Ways to Lower Your Home Insurance Premium
Although insurance costs depend on your circumstances, several strategies may help you manage your premium.
Shop around periodically. Comparing offers from different insurers can help you identify competitive pricing for similar coverage.
Ask about available discounts. Some providers offer discounts for eligible security systems, protective devices, claims-free histories, or other qualifying circumstances.
Review your deductible. A higher deductible may reduce your premium, but choose an amount you could comfortably afford after a covered loss.
Maintain your property. Regular roof inspections, prompt repairs, and proper maintenance can help reduce certain preventable problems, although they do not guarantee lower premiums.
Explore policy bundles. Some insurers offer discounts when eligible homeowners and auto policies are purchased together.
Reassess your coverage regularly. Review your limits when you renovate your home, acquire valuable possessions, or experience other significant changes.
Always compare the total cost and protection offered. A lower premium may not represent better value if it comes with insufficient coverage or unfavorable exclusions.
Common Home Insurance Questions
How much homeowners insurance should I purchase?
Your coverage should reflect the estimated cost of rebuilding your home, the value of eligible personal belongings, your liability needs, and any additional protection appropriate for your location. Your insurer can help you evaluate suitable limits.
Does homeowners insurance pay for roof repairs?
It may cover roof damage caused by an eligible event, depending on the policy. Damage caused by deterioration, poor maintenance, or excluded events may not qualify.
Is my personal property covered outside my home?
Some policies provide limited personal property protection away from the insured residence. Restrictions, coverage limits, and exclusions may apply, so check your policy.
Can I change insurance providers?
Homeowners can generally explore switching providers, subject to their existing contract and other circumstances. If you have a mortgage, ensure the replacement policy meets your lender’s requirements and avoid gaps in coverage.
Is the cheapest quote the best option?
Not necessarily. A less expensive policy may have a higher deductible, lower coverage limits, or more exclusions. Compare the full terms before making your decision.
Make a Confident Decision About Your Home’s Protection
Your home is a significant financial investment, and choosing suitable insurance is an important part of managing the risks associated with ownership.
Take time to understand the coverage available, identify potential gaps, and compare quotes using consistent coverage levels. Reviewing the details before purchasing can help you select a policy that balances protection, affordability, and your household’s financial needs.
Start exploring home insurance quotes today to learn about available options and determine which coverage may be appropriate for your property.
Disclaimer: This article is for general informational purposes only and does not constitute insurance, legal, or financial advice. Coverage availability, policy terms, exclusions, premiums, and discounts vary by insurer and location. Review the official policy documents and consult a qualified insurance professional when necessary.